India’s Insurance Story: Growing Coverage, But a Wider Protection Gap
Forever News
India’s insurance sector stands at an interesting crossroads. On one side, the industry is expanding rapidly, premiums are rising, digital distribution is transforming access and government-backed schemes are bringing millions of people into the insurance ecosystem. On the other, India continues to remain significantly underinsured, with a substantial gap between the financial protection people need and the protection they actually possess.
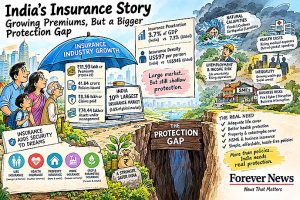
India’s Insurance Protection Gap: Why Insurance for All Still Has a Long Way to Go.
This contradiction deserves far greater attention.
During 2024-25, India’s insurance industry collected premiums of approximately ₹11.93 lakh crore and issued 41.84 crore policies. Claims worth about ₹8.36 lakh crore were paid, while assets under management crossed ₹74.43 lakh crore. India is now the world’s 10th-largest insurance market by premium volume, according to government data based on Swiss Re estimates.
Yet the headline numbers conceal the real challenge.
Insurance penetration in India remained at just 3.7% of GDP in 2024-25—2.7% for life insurance and 1% for non-life insurance. Insurance density rose only marginally to $97 per person, from $95 a year earlier.
In other words, India has a large insurance industry, but not yet a sufficiently insured population.
The paradox of 41.84 crore policies
The number of policies can create a misleading impression of coverage.
One individual can hold several policies, while a family may have a health policy that provides only modest protection against a major hospitalisation. Similarly, owning a life insurance policy does not necessarily mean that the family has adequate income replacement if its principal breadwinner dies.
The distinction between insurance coverage and insurance adequacy is therefore critical.
India’s own Economic Survey has recognised the protection gap and argued that the insurance sector must grow substantially faster than nominal GDP if the country is to strengthen household financial security and reduce vulnerability to financial shocks.
Health insurance: coverage is improving, adequacy remains the question
The health insurance story provides perhaps the clearest example.
The latest National Sample Survey health data shows a dramatic increase in health insurance coverage. Coverage rose from about 14% of the rural population and 19% of the urban population in 2017-18 to roughly 47% in rural India and 44% in urban India in 2025.
That is a remarkable improvement.
But being insured does not necessarily mean being financially protected.
Hospital costs have risen sharply, particularly in metropolitan cities. A policy with a relatively low sum insured, significant exclusions, room-rent restrictions, waiting periods, co-payments or other conditions may leave a family facing substantial out-of-pocket expenditure even after years of paying premiums.
The latest survey estimates average out-of-pocket expenditure per hospitalisation, excluding childbirth, at about ₹34,064, with the urban average at nearly ₹38,700. These figures are averages; serious illnesses and prolonged treatment can generate bills many times higher.
The real question, therefore, is not simply “Are you insured?”
It is “Will your insurance be sufficient when you actually need it?”
The missing middle
India’s insurance challenge is particularly visible among the middle class.
The poorest households increasingly benefit from government-sponsored schemes, while affluent households are more capable of purchasing comprehensive private insurance. Between these two segments lies a large population that may possess some form of cover but remains inadequately protected.
This is the country’s insurance missing middle.
The problem is particularly important because medical inflation, lifestyle diseases, longer life expectancy and increasingly expensive private healthcare are raising the financial consequences of inadequate insurance.
Swiss Re’s research on Asia’s life and health protection gap similarly points to affordability, lack of awareness and the mismatch between products and consumer needs as important barriers. Its 2025 consumer survey found that many households remain worried about medical expenses, while the mortality protection gap across the surveyed Asian markets also remains substantial.
Life insurance: the silent protection gap
The life insurance gap may be even more consequential.
For a salaried or self-employed family, the death of the principal income earner can immediately transform a financially stable household into a vulnerable one.
Mortgage payments continue. Children’s education continues. Household expenses continue. Retirement planning may suddenly disappear.
Yet many Indians still treat life insurance primarily as a savings or tax-planning instrument rather than as an income-replacement mechanism.
That needs to change.
A person earning ₹20 lakh annually may require several crores of financial protection if the objective is to replace future income for dependants. A small traditional policy may technically qualify as life insurance, but it may not provide meaningful protection.
This is where sum assured matters far more than the number of policies.
General insurance is another major opportunity
The protection gap extends beyond life and health.
India’s general insurance penetration remains only around 1% of GDP, compared with a global average of about 4.2% in 2023.
Millions of households remain inadequately protected against fire, floods, natural disasters, accidents and other property-related risks.
The increasing frequency of extreme weather events makes this particularly important.
A home may represent a family’s largest asset, yet household insurance remains relatively uncommon. Small businesses, shops, warehouses and informal enterprises can also face devastating losses from fire, flooding or other disruptions without adequate insurance.
As India urbanises and climate-related risks become more visible, property and catastrophe insurance cannot remain an afterthought.
The industry must also win trust
The next phase of insurance growth cannot be built merely by selling more policies.
It has to be built on trust, transparency and suitability.
Concerns over mis-selling, complicated policy language, unsuitable products and distribution incentives have increasingly entered the regulatory debate. IRDAI is now examining reforms to the economics of insurance distribution, including concerns that incentives can sometimes encourage sales rather than genuine customer suitability.
This is important.
Insurance is a promise made today against a financial crisis that may occur years later. If consumers do not understand exclusions, waiting periods, deductibles, surrender conditions or claim procedures, that promise can become deeply disappointing at the moment of greatest need.
The industry’s future therefore depends not merely on distribution but on better disclosure and better advice.
Technology can narrow the gap
Digitalisation provides an enormous opportunity.
India’s digital public infrastructure, Aadhaar-based identification, UPI ecosystem and expanding digital financial services can make insurance easier to distribute, renew and service.
The government’s push towards Insurance for All by 2047, together with initiatives such as Bima Sugam, is intended to create a more accessible insurance ecosystem. The 2025 insurance-law reforms have also raised the FDI limit in the sector to 100%, potentially bringing additional capital, technology and competition.
But technology alone will not close the protection gap.
A digitally purchased inadequate policy remains an inadequate policy.
The opportunity is enormous
For insurers, the protection gap is not merely a social problem—it is perhaps India’s biggest untapped insurance opportunity.
Swiss Re expects India to remain one of the world’s fastest-growing major insurance markets, forecasting real premium growth of around 7.1% in 2026.
The opportunity lies in moving from a policy-selling culture to a risk-protection culture.
India needs affordable term insurance, adequate health cover, retirement protection, protection for small businesses, crop and climate insurance, property cover and products designed for the informal workforce.
The objective should be simple: when a family suffers a death, illness, accident, natural disaster or loss of livelihood, insurance should prevent that event from becoming a financial catastrophe.
India has made considerable progress.
But the distance between being insured and being adequately insured remains substantial.
That is the real insurance gap—and closing it could become one of the most important pillars of India’s journey towards a financially resilient society.
The ambition of Insurance for All by 2047 should therefore not be measured by the number of policies sold.
It should ultimately be measured by one harder question:
When adversity strikes, how many Indian families can genuinely afford to withstand it?
